Quick answer: Two homes hit by the same storm can get very different claim results because of differences in documentation, how and when the claim was filed, policy coverage (replacement cost vs. actual cash value, percentage deductibles, code coverage), and the adjuster assigned. Getting your roof inspected and documented before the adjuster arrives, and knowing your policy before storm season, are the biggest things you control.
The storm hit your neighborhood. Same wind, same hail, same date. Your neighbor got a full roof replacement. You got a denial, a $600 repair, or an estimate that barely covers the nails. What happened?
Reason 1: Their Roof Was Documented Before the Adjuster Arrived
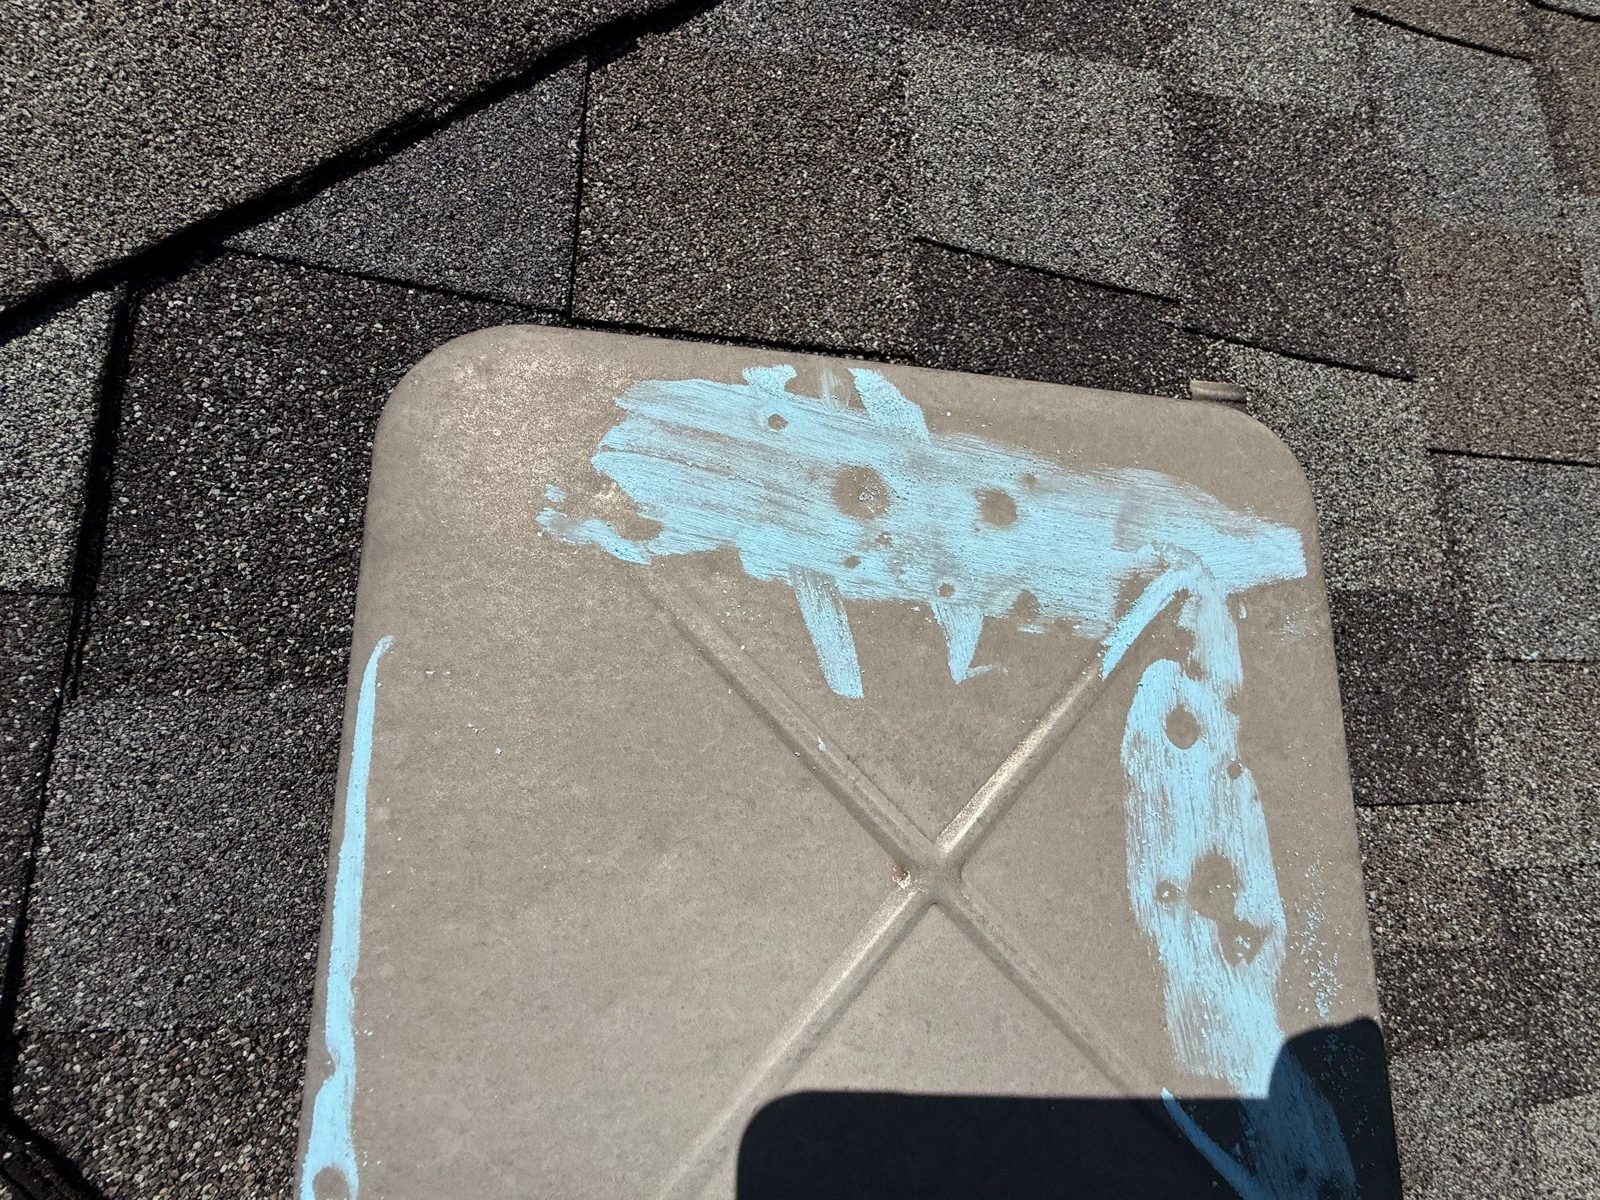
If your neighbor had an experienced roofer inspect first, that roofer likely photographed the damage clearly, tied it to a storm date, and was ready to point it out during the adjuster’s visit. Good documentation makes damage hard to overlook.
Reason 2: Their Claim Was Filed the Right Way
Filing isn’t just calling an 800 number. It means using the correct date of loss, having initial photos and a storm report ready, and knowing what damage to point out. See when and how to file a roof insurance claim.
Reason 3: Your Policies Are Different
This is more common than people realize:
| Your Neighbor | You |
|---|---|
| Replacement cost (RCV) on the roof | Actual cash value (ACV) on the roof |
| Ordinance or law coverage | No code upgrade coverage |
| Flat deductible | 2% wind and hail deductible |
| No cosmetic exclusion | Cosmetic damage exclusion |
One line in a policy can be worth thousands of dollars. Learn more in policy clauses that can sink a roof claim.
Reason 4: You Called Your Agent First
You thought it was the responsible thing to do. Your agent said, “Get three bids and we’ll see if it’s worth filing.” Meanwhile your neighbor had a roofer document the damage and filed directly with the claims department.
Reason 5: You Got a Different Adjuster
Adjusters vary in training and experience. Some are thorough. Others miss damage or default to repairs. Read about the four types of insurance adjusters.
Doing Everything Right Doesn’t Always Feel Like Enough
Honest, patient homeowners sometimes feel penalized: waiting weeks, submitting clean documentation, and still getting underpaid. The answer isn’t exaggeration. It’s being respectful but assertive: follow up consistently, put everything in writing, escalate when a claim stalls, and bring in licensed help, like a public adjuster or attorney, when a dispute warrants it.
How to Keep This From Happening to You
- Have your roof inspected and documented before the adjuster visit.
- Get photos, weather data and a complete scope ready.
- Know your deductible, depreciation rules and exclusions before storm season.
- Escalate in writing if something feels wrong.
Final Thought: Storms Don’t Play Favorites, but Processes Do
It usually wasn’t the hail that made the difference. It was documentation, coverage and process. Now you know what to look for.
Frequently Asked Questions
Why did my neighbor’s roof claim get approved and mine didn’t?
Common reasons include differences in documentation, policy coverage, deductible type, filing timing and the adjuster assigned.
Can I ask for a reinspection if my claim was denied?
Yes. You can request a reinspection, ideally with new documentation from your roofer, and ask for the reason for denial in writing.
Does it help to have a roofer at the adjuster inspection?
It often helps. A roofer can point out documented damage and answer construction questions. The insurer still makes the coverage decision.
Can I reopen a roof claim?
Often, if you’re within your policy’s time limits and have new information or documentation. Ask your insurer about the process in writing.
Get a Second Look at Your Roof
Call or text Bold Roofing for a free inspection with photos.
Texting? Msg & data rates may apply. Reply STOP to opt out.


